

Housing Correction or Housing Crash?
According to the experts
The housing market is not crashing, but it is slowing down. Home prices have been declining since mid-2022, and some experts believe that prices could fall further in the coming months. However, a crash is unlikely, as there are several factors that are supporting the market, such as low inventory, strong demand, and strict lending standards.
The housing market crash of 2008 was caused by a number of factors, including subprime lending, predatory lending, and speculation. In the current market, there are no signs of these same problems. Subprime lending is no longer common, and predatory lending is illegal. Additionally, there is no evidence of speculation in the housing market.
The housing market is currently in a period of correction, which is a normal part of the market cycle. Corrections can be caused by a number of factors, such as rising interest rates, economic uncertainty, or a decline in demand. In the current case, the correction is likely being caused by a combination of factors, including rising interest rates and economic uncertainty.
While the housing market is correcting, it is important to remember that the market is still strong. There is still high demand for housing, and there is still a shortage of inventory. Additionally, lending standards are still strict, which means that buyers are not overextending themselves.
If you are thinking about buying a home, it is important to do your research and understand the market. You should also work with a qualified real estate agent to help you find the right home for your needs.
Highest inflation in history
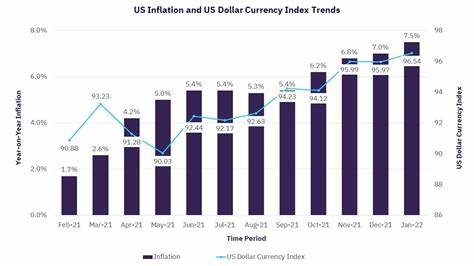
Inflation is at a 40-year high, and that is definitely having an impact on the demand for housing. As the cost of living goes up, people have less money to spend on housing. This is especially true for first-time homebuyers, who are already struggling to save up for a down payment.
Inflation is also making it more expensive to build new homes, which is further reducing the supply of available housing. This is leading to bidding wars and higher prices for the homes that are available.
The housing market is definitely in a tough spot right now, but there are still some reasons to be optimistic. The economy is still strong, and there are still a lot of people who want to buy homes. The market is also starting to cool off a little bit, which could help to make things more affordable.
If you’re thinking about buying a home, it’s important to be patient and to do your research. There are still some great deals out there, but you’re going to have to be prepared to act quickly when you find one.
Highest interest rates in history
High-interest rates can definitely prevent people from buying homes. When interest rates are high, it costs more to borrow money, which means that people have to qualify for larger loans to afford the same house. This can make it difficult for first-time homebuyers to get into the market.
Additionally, high-interest rates can make it more expensive to maintain a home. When interest rates are high, monthly mortgage payments are higher, which means that people have less money to spend on other things, like repairs and maintenance.
Overall, high-interest rates can definitely make it more difficult for people to buy homes. However, there are still some people who are willing to buy homes in this market, especially if they have a stable job and a good credit score.
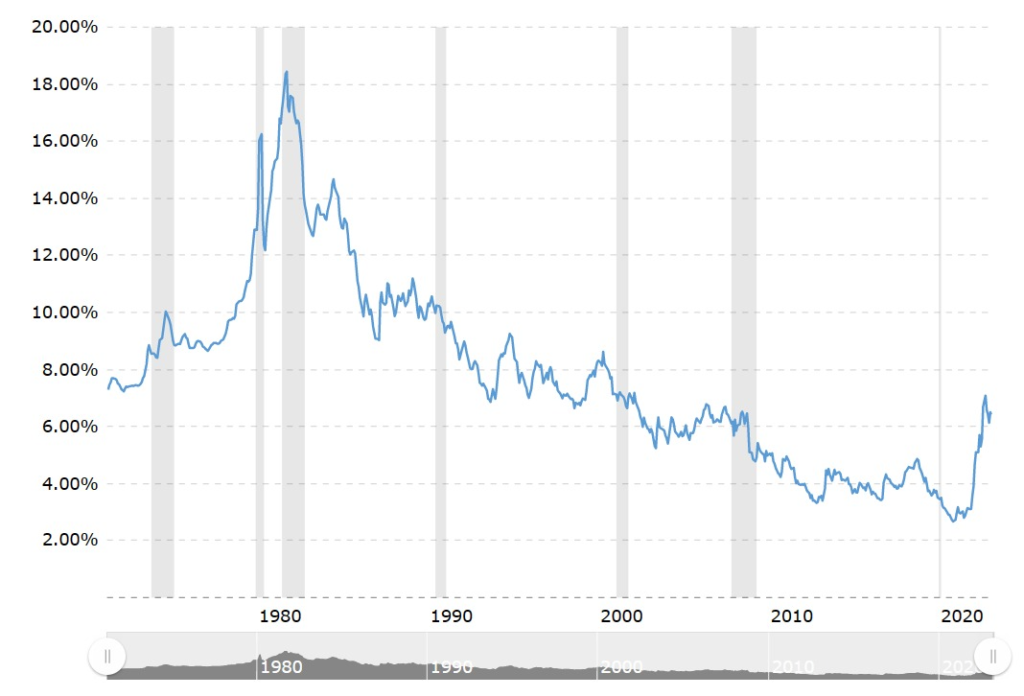
As you can see, the interest rates for all three types of mortgages have been steadily increasing in recent months. The average interest rate for a 30-year fixed-rate mortgage is now 6.81%, which is the highest it has been in over a decade. The average interest rate for a 15-year fixed-rate mortgage is now 5.699%, which is also the highest it has been in over a decade. And the average interest rate for a 5/1 adjustable-rate mortgage is now 5.535%, which is the highest it has been in over 5 years.
These rising interest rates are making it more expensive to borrow money, which is likely to slow down the housing market. However, it is important to remember that the housing market is still strong, and there are still many people who want to buy homes.
You may be interested in, Maximizing Your Outreach: A Step-by-Step Guide to Targeting and Engaging Home Buyers
Conclusion
It is true that higher interest rates can make it more expensive for people to borrow money to purchase homes, which can potentially slow down the housing market.
Nevertheless, it’s important to note that the strength of the housing market depends on several factors, such as supply and demand, economic growth, and job stability. Even if higher interest rates do affect the market, there may still be many people who want to buy homes due to various reasons such as growing families, job relocations, or changing lifestyle needs.
Overall, the housing market can be influenced by a range of factors, and it’s important to consider multiple variables when assessing its strength or weakness.